Start with essential monthly outflow, then adjust for the risks your household actually carries. A practical estimate is: essential monthly expenses × chosen coverage months, plus specific one-time gaps, minus cash already reserved for emergencies. The multiplier is a judgement—not a rule that everyone needs exactly six months.
An emergency fund has one job: provide usable money when an urgent expense or income interruption cannot reasonably wait. It is not an investment-return contest, a holiday fund or the amount shown in your normal spending account.
This guide is educational and does not provide personalised financial, investment, insurance or tax advice. Deposit terms, insurance limits and other rules can change, so verify current official information before making a material decision.
Calculate your emergency fund target
Use this planning formula:
Target = (essential monthly outflow × coverage months) + one-time gaps − existing emergency cash
If income varies, use a cautious estimate of essential outflow and avoid subtracting money already assigned to rent, fees, tax, a medical procedure or another near-term goal.
The result should answer four separate questions:
- What must the household pay each month during a disruption?
- How long might the disruption reasonably last?
- Which urgent costs are not covered by monthly spending or insurance?
- How much accessible cash is already dedicated to this purpose?
Use the site’s emergency fund calculator to record the inputs. Keep the assumptions with the result so a later review can explain why the target changed.
Define essential monthly outflow honestly
Essential outflow is not the same as current total spending, but it is also not a survival budget that the household could sustain for only a week.
| Usually include | Usually separate or reduce |
|---|---|
| Rent or home-loan payment | Discretionary shopping |
| Basic food and household supplies | Optional subscriptions |
| Utilities and essential communication | Leisure travel and eating out |
| Transport needed for work or care | Voluntary extra debt payments |
| Insurance premiums | New long-term investments |
| Medicines and routine healthcare | Planned large purchases |
| School or care costs that cannot pause | Expenses that would genuinely stop with income |
| Minimum debt payments | Annual costs already covered by a sinking fund |
Look at several months of statements. Include quarterly or annual essentials by converting them to a monthly amount. For example, a ₹24,000 annual premium adds ₹2,000 to monthly outflow unless it already has a separate fully funded account.
For a two-income household, do not automatically halve expenses on the assumption that only one income can fail. Some emergencies affect both incomes or increase costs at the same time. Model the event that matters, then decide how much risk the household can accept.
Choose coverage months from household risk
The Reserve Bank of India’s financial-education workbook gives at least three months of living expenses as a general emergency-fund starting point and notes that people with less secure income may need more (RBI financial-education workbook). That is guidance, not a compulsory national standard.
Use a smaller or larger planning range based on evidence:
| Factor | Why it may change the target |
|---|---|
| Two stable, independent incomes | A single job loss may leave some household income intact |
| One household income | The whole budget depends on one interruption risk |
| Freelance, seasonal or commission income | Recovery time and monthly income may be unpredictable |
| Dependants | More essential costs may be difficult to reduce quickly |
| Limited insurance or high deductible | More urgent costs may fall directly on cash reserves |
| Specialist role or local job market | Re-employment could take longer |
| Strong family support or reliable alternate income | May reduce the cash burden, if that support is genuinely available |
| Planned career break or known expense | This is not an emergency; fund it separately |
Three months may be a useful first milestone for a stable household. Six or more may be more realistic when income is concentrated or hard to replace. A self-employed person with volatile receipts may also keep a separate business reserve so business and household risks are not mixed.
Do not keep raising the target simply because more cash feels safer. Beyond a sensible contingency level, holding too much for years can delay other goals and lose purchasing power after inflation. The target should be defensible, not endless.
Add one-time gaps and subtract only dedicated cash
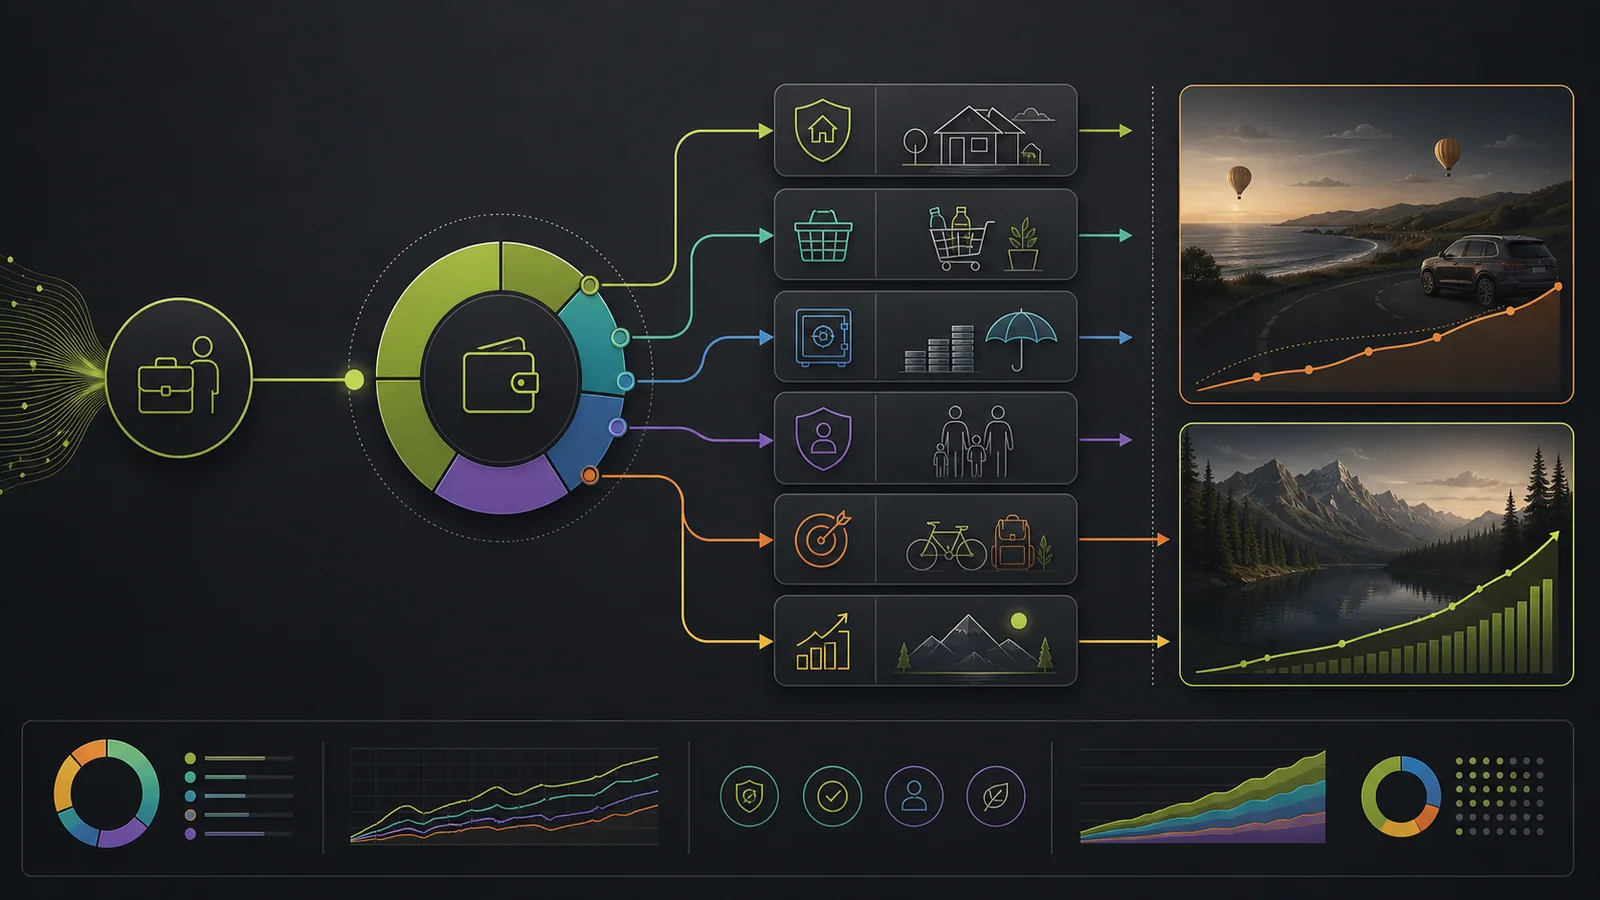
The monthly multiplier may miss costs that arrive as a lump sum. Add amounts that are both plausible and not already covered, such as:
- an insurance deductible or known coverage gap;
- urgent travel to support a family member;
- essential home or vehicle repair needed for work;
- a temporary increase in care costs; or
- a rent deposit if loss of employer housing is a realistic risk.
Avoid adding every imaginable disaster. Insurance, public support, family resources and other protections may handle some risks more efficiently than cash. The exercise is to cover a credible gap, not to make uncertainty disappear.
Subtract only money that is accessible, stable in value and explicitly reserved for emergencies. Do not subtract:
- next month’s bill money;
- an equity investment that might be down when needed;
- a credit-card limit;
- a loan you have not qualified for; or
- an asset that would take weeks to sell.
Credit can bridge payment timing in some cases, but it is not a fund. A lender can reduce a limit, charge high interest or decline an application during the same disruption.
Worked example: target and monthly saving
Consider a household with ₹50,000 of essential monthly outflow. Its income is concentrated in one salary, so it chooses six months as a planning scenario. It adds ₹40,000 for a realistic insurance and urgent-travel gap and already has ₹80,000 in dedicated emergency cash.
| Calculation | Amount |
|---|---|
| ₹50,000 × 6 months | ₹3,00,000 |
| Add one-time gaps | + ₹40,000 |
| Subtract existing reserve | − ₹80,000 |
| Remaining amount to build | ₹2,60,000 |
At ₹20,000 per month, the remaining gap takes 13 months, ignoring any interest. At ₹10,000 it takes 26 months. That time-to-target is often more useful than the target alone.
If ₹20,000 is not available, create milestones: perhaps ₹25,000 first, then one month of essential expenses, then three months, and finally the risk-based target. A partial reserve still reduces the chance that the next problem becomes expensive debt.
Keep the fund accessible and stable
Emergency money should be available quickly, easy for the right household member to access and unlikely to fall sharply in value. No single account has to hold the whole amount.
A simple layered approach is:
- a small amount available immediately for payment-system or local disruptions;
- a core amount in an accessible bank account or deposit with understood withdrawal terms; and
- any additional layer in a low-complexity option whose liquidity, value risk, costs and tax treatment you understand.
Do not assume “liquid” means instant, stable or cost-free. Check settlement time, cut-off rules, holidays, exit charges and what happens outside banking hours. Keep access instructions secure and ensure an appropriate family member knows the process without sharing PINs, passwords or OTPs.
For bank deposits, understand deposit insurance rather than relying on a bank label. DICGC currently insures eligible deposits up to ₹5 lakh per depositor per bank in the same right and capacity, including principal and interest; balances at different branches of the same bank are aggregated. Deposits in separate insured banks are covered separately. Verify that a bank is insured and read the current rules on DICGC’s website (DICGC guide to deposit insurance; DICGC insured banks). This limit was checked on 14 September 2026 and should be rechecked before relying on it.
Balance emergency saving with expensive debt
“Pay all debt first” and “finish six months of savings first” can both be poor blanket advice. With no cash buffer, a minor expense may go straight back onto an expensive card. With costly revolving debt, slowly building a very large cash balance can also waste substantial interest.
A practical sequence is:
- Stay current on required payments.
- Build a small starter buffer for immediate surprises.
- Direct more cash toward expensive debt while continuing a manageable reserve contribution.
- Expand the emergency fund as the expensive balance falls.
Compare the debt’s actual annual cost, penalties and repayment terms. Do not borrow to create the appearance of an emergency fund. For the wider order of goals, protection, debt and investing, use the personal financial plan guide.
Decide what qualifies as an emergency
A clear rule prevents the reserve from becoming a general savings account. A withdrawal should normally meet all three tests:
- necessary: not paying would cause meaningful harm;
- urgent: it cannot reasonably wait for normal cash flow; and
- unplanned: it was not a known recurring or scheduled expense.
Job loss, urgent uncovered treatment or an essential repair can qualify. A sale, routine festival spending, annual premium or planned holiday does not. Known irregular expenses need sinking funds with their own deadlines.
When the fund is used, record the amount and reason, then create a refill plan after the immediate pressure passes. There is no value in feeling guilty about a valid withdrawal—the reserve existed for that event.
Review the target after major changes
Review at least annually and after a change in income, dependants, housing, debt, insurance or health. Recalculate essential outflow from recent statements rather than increasing last year’s target by habit.
Check four operational details as well:
- Can the money be accessed within the required time?
- Are account nominees and contact details current?
- Does the household know which expenses to reduce first?
- Is the reserve separate enough to avoid casual spending?
Once the full target is reached, redirect the monthly contribution to the next priority instead of continuing indefinitely. For long-term, market-linked goals, the SIP calculator guide explains how to estimate a goal-based contribution. Emergency money itself should not depend on a favourable market day.
The right emergency fund is not the largest balance you can imagine. It is a deliberate amount tied to essential costs, realistic household risks and reliable access. Calculate it, build it in stages, and let it do its unglamorous job when life stops following the budget.
Sources
Built from product experience