A retirement corpus should be built from the spending it must support—not from a universal multiple of salary. Estimate expenses at retirement, subtract dependable income, decide how long the remaining assets may need to last, and test the result under several inflation, return and longevity assumptions.
The difficult part of retirement planning is not producing one large number. It is recognising that the number changes when retirement age, living costs, healthcare, family responsibilities, inflation or investment performance changes. A useful plan keeps those assumptions visible and gives you actions for both accumulation and withdrawals.
This guide is educational, not personalised investment, tax, insurance or legal advice. The examples are illustrations, returns are not guaranteed, and pension and tax rules can change. Verify current official rules before acting.
Start retirement planning with spending, not current salary
List what the household expects to spend in retirement in today’s rupees. Divide it into categories so the assumptions can be challenged later.
| Expense group | What to consider |
|---|---|
| Core living costs | Food, utilities, transport, maintenance, household help and communication |
| Housing | Rent or maintenance, repairs, property tax and the possibility that a loan continues |
| Healthcare | Premiums, deductibles, medicines, routine care and costs not covered by insurance |
| Family commitments | Support for parents or adult children and any planned gifts |
| Lifestyle | Travel, hobbies, eating out and other flexible spending |
| Irregular replacements | Vehicle, appliances, home repairs and assistive equipment |
Do not simply take 70% or 80% of salary. Salary is not spending, and two households with the same income can need very different retirement cash flows. Some work-related costs may disappear, while healthcare, help at home or travel may rise.
Separate one-off goals from recurring retirement spending. A home renovation at retirement, a child’s education and monthly living costs should not be blended into one unexplained corpus.
Translate today’s spending to the retirement date
If annual retirement spending would be ₹6 lakh in today’s money and retirement is twenty years away, inflate that amount:
First-year expense at retirement = today’s annual expense × (1 + inflation rate)^years to retirement
At an illustrative 6% annual inflation rate, ₹6 lakh becomes about ₹19.24 lakh after twenty years. That is not a forecast. It shows how strongly a long horizon magnifies the inflation assumption.
Test at least a lower and higher inflation scenario. Healthcare or rent may not move like a broad consumer-price measure. If the household expects to own its home, do not set housing expense to zero—maintenance, repairs, taxes and possible accessibility changes remain.
Keep the values in two views:
- Today’s rupees make the lifestyle understandable.
- Future rupees show the amount that may actually need to be paid.
Confusing the two is one of the fastest ways to understate a retirement target.
Choose a planning horizon that can survive uncertainty
The horizon runs from retirement until the assets no longer need to support the household. Nobody knows that date in advance. Planning only to average life expectancy can leave a serious tail risk.
Consider:
- the age and health of both partners;
- the younger partner’s potential horizon;
- family longevity without treating it as certainty;
- whether dependants may still need support; and
- whether later-life care could increase spending.
Run more than one horizon—for example, the central plan plus a longer-life scenario. Early retirement creates a double effect: fewer working years to contribute and more retirement years to fund.
The result should not be interpreted as a promise that a corpus will last. It is a planning range that needs periodic review.
Subtract only income you can reasonably rely on
List retirement income separately from assets:
| Possible source | Questions before counting it |
|---|---|
| Defined pension or annuity | Is it guaranteed, inflation-linked, joint-life and subject to conditions? |
| Rental income | What remains after vacancy, repairs, tax and management costs? |
| EPF or other retirement balance | Will it be retained, withdrawn or already used for another goal? |
| NPS | What portion may support withdrawals or annuity under the rules then in force? |
| Part-time work | Is it a preference or a necessity, and how long is it realistic? |
Distinguish income from assets that must be drawn down. A mutual-fund balance is not a pension simply because periodic withdrawals are planned. Counting both the full balance and its future withdrawals as separate resources double-counts the same money.
Use after-cost, after-tax estimates where possible, but do not hard-code current tax treatment decades into the future. Verify rules nearer each decision.
Estimate the corpus as a range, not one precise answer
The retirement corpus is the amount needed at retirement to fund the spending gap after reliable income. A detailed model projects yearly spending and withdrawals. A rough multiple of the first-year gap can be used as an early sense-check, but it is not a universal safe-withdrawal rule.
Suppose the first-year retirement spending is ₹9 lakh and dependable after-tax income is estimated at ₹3 lakh. The first-year gap is ₹6 lakh.
| Illustrative multiple of first-year gap | Starting corpus |
|---|---|
| 20× | ₹1.20 crore |
| 25× | ₹1.50 crore |
| 30× | ₹1.80 crore |
The table does not say any of those amounts is sufficient. A higher multiple generally provides more room for a long horizon, weak early returns or lower future returns, but the result also depends on inflation, fees, taxes, asset mix and spending flexibility. Indian investors should not import a withdrawal rule from a different market and treat it as a guarantee.
For a fuller projection, model annual cash flows:
- Increase spending by the inflation assumption.
- Add reliable income and any income escalation separately.
- Withdraw the gap from the portfolio.
- Apply investment returns and costs to the remaining balance.
- Repeat through the selected horizon.
Test poor returns early in retirement, not only a smooth average. Two portfolios can earn the same long-term average but have very different outcomes when withdrawals begin during a market fall.
Work backwards to the monthly investment
Once you have a retirement-date target, subtract the projected value of assets already dedicated to retirement. Then estimate the monthly contribution required over the remaining working years.
Use the retirement calculator to vary current expenses, retirement age, inflation and return assumptions. Preserve the inputs alongside the result. A number without its assumptions cannot be reviewed.
If the required contribution is unaffordable, use levers you control:
- increase the current contribution;
- raise it gradually when income rises;
- retire later if health and employment allow;
- reduce flexible retirement spending;
- direct appropriate existing assets to retirement; or
- revisit other lower-priority goals.
Do not close the gap by increasing the assumed return alone. That changes the spreadsheet, not the household’s capacity to bear risk. The SIP calculator guide explains contribution timing and scenario testing for recurring investments.
Build separate plans for accumulation and retirement income
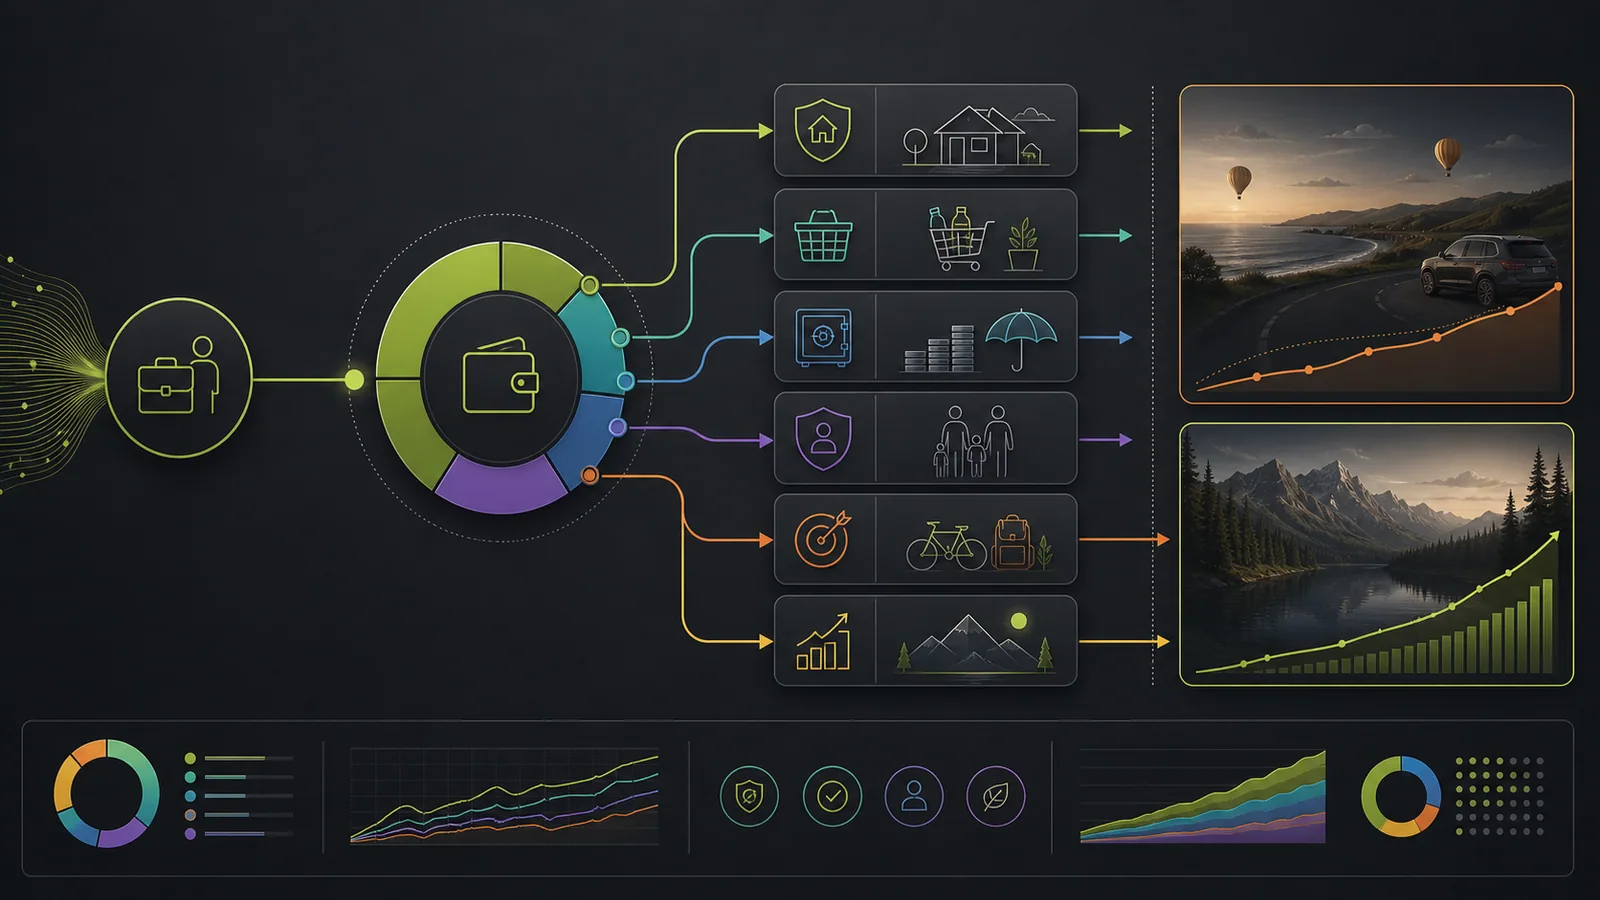
Before retirement, the portfolio’s job is to accumulate enough assets while surviving market declines. During retirement, it must also provide cash on schedule. Those are related but different problems.
A practical retirement-income structure may separate:
- near-term spending that needs high liquidity and stability;
- medium-term spending that needs some protection from inflation; and
- long-horizon assets that can accept more fluctuation.
This is a planning concept, not a prescribed asset allocation. The right proportions depend on spending flexibility, other income, risk capacity and product constraints.
Reduce reliance on forced sales after a market fall by keeping appropriate near-term liquidity. But holding the entire retirement corpus in cash can create inflation and longevity risk. The decision is a balance, not a choice between “safe” and “risky.” SEBI’s Riskometer can help identify the stated risk level of a mutual-fund scheme, though it does not decide whether the scheme suits a household (SEBI Riskometer).
Fit EPF, NPS and insurance into the plan carefully
EPF, NPS, gratuity, pensions and insurance can materially change an Indian retirement plan, but each has its own eligibility, liquidity, tax and withdrawal rules.
NPS is a regulated, market-linked defined-contribution system rather than a guaranteed corpus. PFRDA describes its structure, choices and intermediaries, and publishes the regulations governing exits and withdrawals (PFRDA overview of NPS; PFRDA regulations). Check the rules effective when a contribution, withdrawal or annuity decision is made; an old article can become wrong after an amendment.
Health insurance does not eliminate the need to plan for medical spending. Premiums, exclusions, deductibles, non-covered treatment and care outside hospital can still affect cash flow. Review coverage before employer benefits end, when choices may become more limited or expensive.
Life cover may become less important once nobody depends on employment income, but do not cancel it solely because retirement begins. Check liabilities, dependants, estate needs and policy terms first.
Stress-test the plan before trusting it
At minimum, compare scenarios for:
- retirement earlier or later than planned;
- higher inflation, especially healthcare inflation;
- lower investment returns after costs;
- a market fall near retirement;
- a longer planning horizon;
- loss or delay of expected income;
- a large medical or family expense; and
- lower spending after an adverse outcome.
A plan is more resilient when it has responses, not only risks. Decide which spending can be reduced, whether work could continue, which assets are genuinely available and how much near-term liquidity would prevent a forced sale.
Keep an emergency reserve outside the ordinary retirement spending calculation. The appropriate amount may change after retirement because income is less replaceable and healthcare needs may rise.
Review the plan at each major transition
Review annually during accumulation and more often in the years around retirement. Update balances, spending, inflation assumptions, expected income, insurance, nominees and the planned asset mix. Review immediately after job loss, a health event, a major market move that changes the allocation, or a regulatory change affecting a material benefit.
As retirement approaches, replace estimates with facts: obtain current benefit statements, verify pension options, map the first few years of cash flow and check who can access records if you cannot. Do not share account passwords, PINs or OTPs; use proper nominations, mandates and estate documents.
Retirement planning in India is not about finding the most impressive corpus target. It is about connecting future household spending to dependable income and a portfolio that can cope with imperfect returns, long life and changing needs. A range you understand and review is more useful than a precise number built on hidden optimism.
Sources
Built from product experience