To work out how much to invest in a SIP for a goal, start with the goal's cost and date, inflate the cost to that date, subtract money already set aside for it, and calculate the monthly amount that closes the gap under a few return assumptions.
- Start a SIP calculation with a goal and a date, then work backwards to the monthly amount.
- Inflate the goal cost, subtract only assets already reserved for it, and calculate the funding gap.
- Test several return assumptions; if the answer is unaffordable, change the contribution, goal or timeline rather than the return.
- Use a step-up only when future income can genuinely support it.
- Review progress against the goal at least once a year.
A systematic investment plan, or SIP, is a way to invest a fixed amount in a mutual-fund scheme at regular intervals. It encourages consistency but does not make the scheme safe or guarantee the projected value. Scheme choice, market performance, costs, taxes, missed instalments and withdrawals all affect the result. All returns below are illustrations.
Ask the calculator the right question
A SIP calculator can answer two questions:
- What might my chosen monthly SIP become? A future-value projection.
- How much might I need to invest each month for a target? A goal-based contribution estimate.
The second is usually more useful. "I invest ₹10,000 a month" describes an activity; "I am building an inflation-adjusted education fund for 2036" describes a purpose you can monitor.
Before calculating, write down:
| Input | What it should mean |
|---|---|
| Goal cost today | A current estimate for the actual expense |
| Years remaining | Time until the money must be available |
| Inflation assumption | A scenario for how the goal's price may change |
| Existing goal assets | Money genuinely reserved for this goal, excluding the emergency fund |
| Return assumptions | A range consistent with the investment risk being considered |
| Contribution timing | Beginning or end of each month |
| Costs and taxes | Reflected where material; a headline return is not what you keep |
A calculator can perform flawless arithmetic on an unrealistic assumption, so the inputs deserve the most attention.
Estimate the goal and the funding gap
If a goal costs ₹10 lakh today and is ten years away, entering ₹10 lakh as the target ignores rising prices:
Future goal cost = current cost × (1 + inflation rate)^years
At an assumed 6% annual inflation rate, ₹10 lakh becomes about ₹17.91 lakh after ten years. That makes the assumption visible; it does not predict the price. Test a lower and higher rate, especially when the goal's cost may not follow general inflation.
Subtract only assets already dedicated to the goal, projected separately if they will also grow. Do not subtract the same investment from both a child's education target and retirement.
Funding gap = future goal cost − projected value of dedicated assets
If the gap is zero or negative, the task becomes protecting the goal from unnecessary risk and checking whether the assumptions still hold.
Calculate the monthly SIP from the gap
For equal contributions at the end of each month:
Monthly contribution = target × monthly rate ÷ ((1 + monthly rate)^number of months − 1)
Monthly rate = (1 + annual return)^1/12 − 1
Some calculators divide the annual rate by 12 or assume beginning-of-month contributions, so answers differ slightly. A good calculator discloses its method. When the assumed return is zero, the answer is simply the target divided by the number of contributions.
Worked example (illustrative): a ₹20 lakh funding gap, 120 end-of-month contributions, no pauses, withdrawals, costs or taxes.
| Illustrative annual return | Approximate monthly SIP |
|---|---|
| 6% | ₹12,310 |
| 8% | ₹11,103 |
| 10% | ₹10,007 |
Moving from 6% to 10% reduces the displayed requirement by about ₹2,300, but the goal has not become cheaper; the calculator has assumed a better market outcome. A practical plan might choose a contribution based on the cautious scenario and review annually. Better performance creates a buffer; worse performance shows up early enough to respond.
Use the site's step-up SIP calculator to compare a fixed contribution with one that rises annually, and record the assumptions so the result can be reproduced.
Use a step-up only when future cash flow supports it
A step-up SIP raises the monthly contribution at a chosen interval, usually each year. It can reflect salary growth and lower the amount needed today, but it also produces a misleadingly comfortable starting figure if the increases never happen.
A 10% annual step-up means your contribution rises, not your returns. If ₹10,000 a month becomes ₹11,000 next year, the extra ₹1,000 comes from future cash flow. Use a step-up when income is reasonably likely to grow, the increase stays affordable after essentials, and you have a reminder or automatic instruction to make the change. Freelancers and households planning a career break may prefer a sustainable base amount plus occasional top-ups.
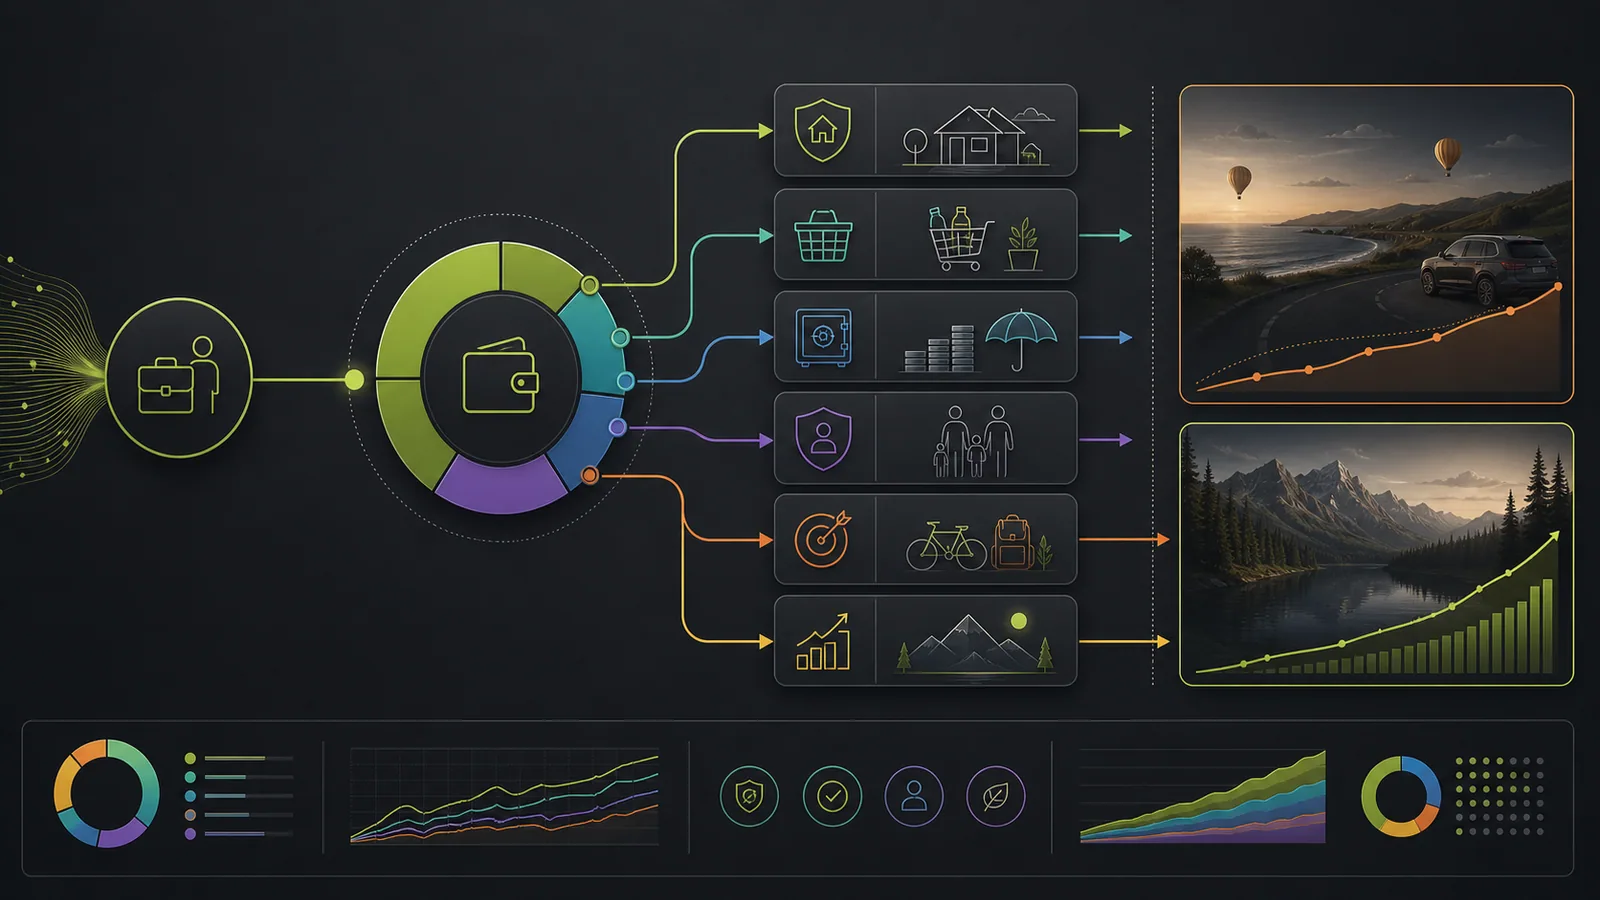
YojIQ handles this as the last of its four plan steps: once the emergency fund, health insurance and term insurance steps are covered, you set SIP goals with an optional yearly step-up. Your salary and appraisal history in the app gives a realistic basis for the step-up rate.
Choose return assumptions, costs and tax carefully
A SIP is a method, not an asset class. The underlying scheme may hold equity, debt, a mix or a narrow theme, each with different risks. AMFI describes SIP as an investment methodology offered by mutual funds, and SEBI's own calculator warns that market returns are not fixed or predictable (AMFI on mutual funds and SIPs; SEBI SIP calculator).
Start with the goal's horizon and tolerance for delay or loss. A high-risk scheme does not suit a near-term fixed commitment merely because you invest monthly. SEBI's Riskometer shows a scheme's stated risk level from low to very high, but you still need to read the scheme documents and assess fit (SEBI Riskometer). Use a range of returns, including a weak scenario, and for important goals test a fall close to the withdrawal date, which an average return hides. The investment risk profiler can help you think through that tolerance.
Calculator outputs usually ignore frictions. Check the expense ratio, direct versus regular plan costs, exit loads, current tax rules on redemption and whether the money is accessible when needed. Each instalment buys units on a different date, so exit loads can apply separately to each (SEBI guide to exit loads). Direct plans exclude distributor commission; regular plans include intermediary support, which some investors genuinely need (SEBI guide to direct and regular mutual funds). Do not hard-code an old tax rate or scheme charge into a long-term plan.
Protect your resilience and review progress
A calculator sees a target, rate and timeline. It cannot see an unstable salary, uninsured medical exposure or expensive debt. Before raising a market-linked contribution, check that essential bills are current, an emergency reserve is being built and high-cost debt has a plan. See the emergency fund calculator guide, or step back to the personal financial plan when several goals compete for the same surplus. Reducing a SIP during a genuine cash-flow emergency can be rational; the mistake is not updating the goal forecast afterwards.
Review at least annually and whenever the goal cost, timeline, income or existing assets change:
- Is the estimated future goal cost still reasonable?
- Are contributions happening as planned?
- Is the asset mix still suitable as the goal approaches?
- Is the current value ahead of or behind the modelled range?
- If there is a shortfall, can the contribution, deadline or goal change?
As the goal becomes near-term, reducing market risk may matter more than pursuing the original return assumption. A good SIP calculator gives you a contribution range and exposes the trade-offs; keep the assumptions and change the plan when reality differs.